
News: Suppliers
11 November 2026
Aixtron’s revenue grow 60% in Q3, driven by opto demand for AI data centers
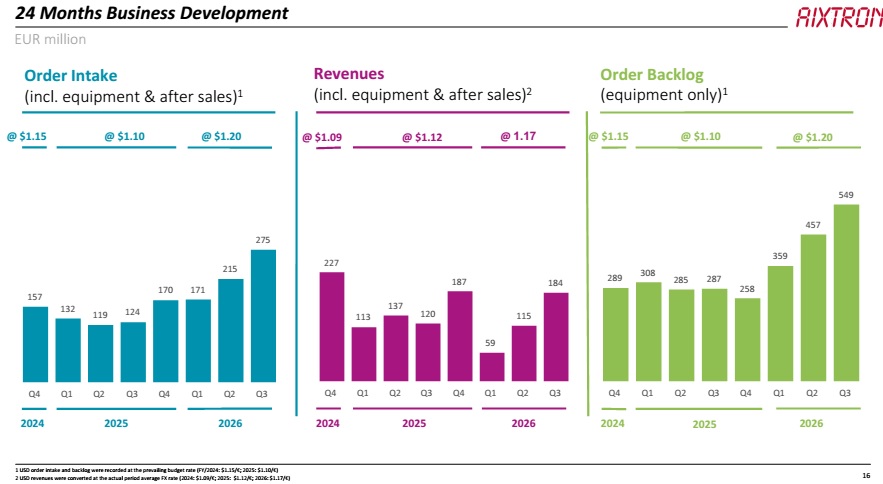
For third-quarter 2026, deposition equipment maker Aixtron SE of Herzogenrath, near Aachen, Germany has reported revenue of €183.6m (within the guided range of €180m±€20m), up 60% on Q2’s €115.1m and up 54% on €119.6m a year ago, recovering further from the trough of €59m in Q1.
This reflects the ongoing ramp-up in optoelectronics business as well as the continued emergence from Q1’s trough in power electronics.
For the first nine months 2026, revenue was €358.1m, down 3% on €369.5m the prior year.
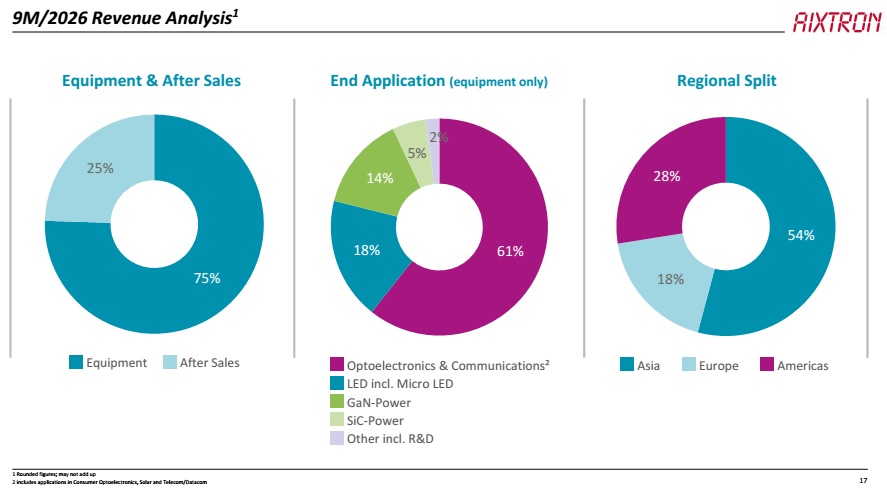
After-sales contributed €87.8m (25% of revenue), up 10% year-on-year from €79.7m (22% a year ago.
Equipment revenue contributed €270.3m (75% of revenue), down 7% on €289.8m (78% of revenue)
Of the equipment revenue, optoelectronics accounted for 61%, gallium arsenide GaN and silicon carbide SiC power electronics for 19%, and LEDs & micro-LEDs for 18%.
Of total revenue by region, Asia fell year-on-year from 60% (€221.6m) to 54% (€193.9m), while the America rose from 23% (€83.3m) to 28% (€98.5m). Europe rose slightly from 17% (€64.6m) to 18% (€65.7m).
Profitability boosted by favorable product and regional mix
Driven by the higher revenue and the better product mix and regional mix, quarterly gross margin has risen further, from 39% a year ago and 41% last quarter to 48% in Q3/2026.
Operating expenses were €30.6m, roughly level with €30.9m a year ago. This consisted mainly of R&D spending of €22.8m (albeit down from €23.7m a year ago).
Operating result (EBIT) was €56.7m (EBIT margin of 31% of revenue), up on just €14.7m last quarter and €15.4m (13% margin) a year ago, boosted by operating leverage due to the higher revenue volume.
Net profit was €35.4m (€0.31 per share), up almost doubling from €19.1m (€0.17 per share) last quarter and almost tripling from €13m (€0.11 per share) a year ago.
Cash flow more than triples year-on-year
Operating cash flow was €138.4m, up from last quarter’s €119m and more than tripling from just €43.4m a year ago. This is driven mainly by higher customer pre-payments of €309m, up from just €44m at year-end 2025 (reflecting the strong order intake and backlog, the favourable composition of orders, and individually agreed payment terms), supporting the upcoming production ramp.
Free cash flow was €127.8m (up on €113.6m last quarter and more than tripling from just €39.2m a year ago).
As of end-September, cash and cash equivalents (including other current financial assets) were hence €944.8m (up from €816.2m at the end of Q2/2026 and – boosted by the placement in April of the firm’s inaugural convertible bond, of €450m – up from €224.6m at end-December 2025).
After deducting the liability component of the convertible bond of €353.9m, net financial assets amounted to €590.9m, up from €467m at the end of Q2 and €225m at year-end 2025.
The equity ratio has fallen further, from 88% at year-end 2025 and 61% at the end of Q2/2026 to 58% at the end of Q3, primarily reflecting the increase in total assets following issuance of the convertible bond.
“Our strong financial position provides us with the strategic flexibility to advance Aixtron’s development,” says chief financial officer Dr Christian Danninger. “It enables us to invest in our technology roadmap, strengthen our capabilities and further expand our position in attractive growth markets, creating sustainable long-term value.”
Market & business development, order intake
Order intake was €274.9m, up 40% on €214.5m last quarter and more than doubling (up 122%) on €124m a year ago, driven predominantly by optoelectronics for AI data centers and, increasingly, also by power electronics. Of equipment orders:
- 68% was for optoelectronics applications (driven by laser applications in AI data-center communications), as demand for InP-based optical components continues to exceed original expectations and grow rapidly. The expansion of AI data-center networks remains the key structural driver for transceivers and InP in high-speed optical interconnects.
Industry investment spans both 800G and 1.6T optical transceiver market: While 800G remains the established volume platform, the transition to 1.6T is expected to progress gradually as customer qualifications and supply chains mature. - 24% was for power electronics applications, as momentum in GaN and SiC power electronics continued to improve in Q3. Initial orders for capacity expansions and a growing pipeline indicate the beginning of a recovery in power electronics, driven mainly by emerging low-voltage GaN applications for AI infrastructure power delivery (800V HVDC power) as well as industrial and AI-related high-voltage SiC applications. “Improving customer utilization, renewed order activity and preparations for new capacity provide increasing evidence of a recovery in GaN and SiC power electronics,” notes CEO Dr Felix Grawert. Broad market demand for GaN is expected to kick in once low-voltage adoption becomes broader. For SiC, customer utilization and consumables consumption is improving, and Aixtron has received the first new orders for 200mm capacity expansions.
“Together, these trends reinforce our expectation of a strong growth year in 2027, led by optoelectronics,” Grawert adds.
In contrast, LED/micro-LED system demand remains soft. However, AR and AI optical interconnect activity is increasing. So, the long-term opportunity remains attractive, reckons Aixtron.
Order backlog rising despite production ramp
To serve all customers with shipments at their requested delivery dates, Aixtron is increasing manufacturing output at its own premises and in close cooperation with its suppliers. Output has risen each quarter throughout 2026 and is expected to increase further in Q4/2026.
Despite production continuing to ramp up during the year, equipment order backlog reached €549.4m, up on €456.9m at end-June and up 92% on €286.5m a year earlier (and more than doubling from €257.8m at year-end 2025).
Most of the order backlog consists of equipment for InP-based optical applications, providing revenue visibility well into 2027.
In addition to the strong order intake and order backlog, the composition of current orders and individually agreed payment terms also had a slightly positive impact on customer advance payments, (€197m, 43% of the equipment order backlog, in Q2). These advance payments contribute to financing the upcoming volume production ramp.
Inventories rose from €283.6m at end-2025 to €323.3m at end-Q3/2026, mainly reflecting higher levels of work in progress (WiP) for shipments scheduled in the coming quarters.
Full-year 2026 guidance confirmed - strong outlook for 2027
Supported by the strong order backlog, in Q4/2026 Aixtron expects a further increase in output and revenue growth to about €200m.
For full-year 2026, Aixtron has hence confirmed its revenue guidance, which on 14 April was raised from €520m±€30m to €560m±€30m.
Of this, Q4/2026 revenue is expected to be up sequentially to €200m±€30m (comprising €170m±€30m from the equipment order backlog and €30m in after-sales revenue).
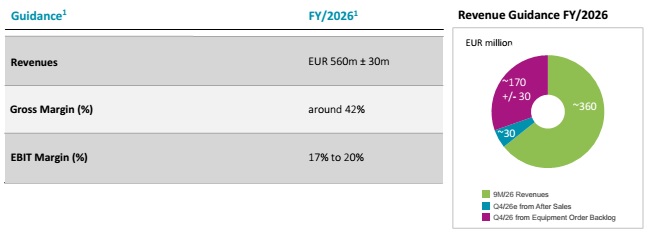
Aixtron also expects to achieve the raised guidance for gross margin of about 42% and for EBIT margin of 17–20%. This includes one-off expenses in the mid-single-digit-million Euro range related to the personnel reduction in operations in Q1 to create a more flexible operating structure after the very soft business outlook at the beginning of 2026 (this follows a prior 10% staff reduction between mid-2025 and mid-2026, from 1155 to 1035).
Based on the current sales pipeline, Aixtron expects to maintain or further grow the current strong order intake over the coming quarters, led by demand for optoelectronics and increasingly by growing momentum in power electronics. Significant growth is therefore expected in 2027.
Aixtron now expects capital expenditure of about €40m (rather than the prior €55m) for full-year 2026. This comprises baseline investments and about one-third of the announced €40m investment in the Malaysia expansion (rather than the previously forecasted two-thirds), with the remainder shifting to next year due to timing.
Malaysia expansion progressing according to plan
Construction of Aixtron’s new manufacturing facility in Penang, Malaysia [a €40m investment in 2026–2027, announced in March], remains fully on schedule. The ground work and piling have been completed, the ground floor is almost finished, and Aixtron expects to be able to use the building from fall 2027 onwards, for first system shipments by end-2027. Located in a leading semiconductor ecosystem, the site will add manufacturing flexibility (expanding Aixtron’s manufacturing capacity by 25–30% by 2028), strengthen supply-chain resilience, support future growth and enhance long-term cost competitiveness, it is expected.
Aixtron’s revenue almost doubles in Q2/2026, driven by opto boom
Aixtron’s Q1 revenue down 47% year-on-year, but opto drives 30% growth in orders
Aixtron to build new manufacturing plant in Malaysia
Aixtron’s Q3 revenue and margin impacted by volume shifts into Q4