
News: Microelectronics
16 November 2026
Wolfspeed’s revenue rebounds by 3.6% in September quarter to $155m
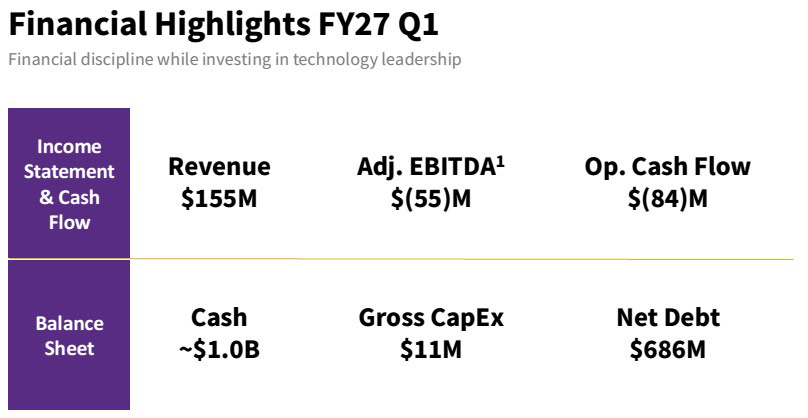
For its fiscal first-quarter 2027 (to 27 September 2026), Wolfspeed Inc of Durham, NC, USA — which makes silicon carbide (SiC) materials and power semiconductor devices — has reported revenue of $155m, down 21% on $196.8m a year ago but recovering by 3.6% from $149.6m last quarter, and exceeding the midpoint of the $140–160m guidance range.
Materials Products revenue has fallen further, from $65m a year ago and $43.3m last quarter to $38.2m (driven largely by a tightening demand environment and increased competition in the market, while reflecting the ongoing supply of silicon carbide materials to a broad range of customers).
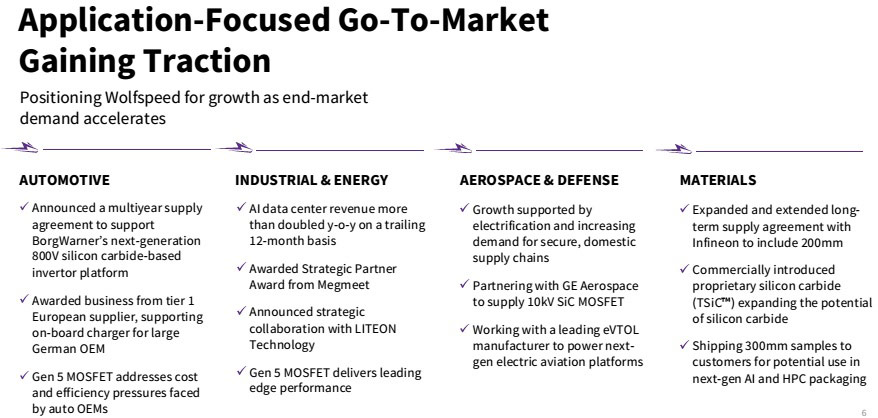
Power Products revenue was $116.8m, still down on $131.8m a year ago but recovering further, by 10%, on $106.3m last quarter, driven by demand from the Industrial & Energy (I&E) end-market. This includes AI data-center business, which again comprised the firm’s highest-growth sector (with demand increasing for high-voltage direct current architectures), consistent with last quarter’s revenue and more than doubling year-on-year on a trailing 12-month basis.
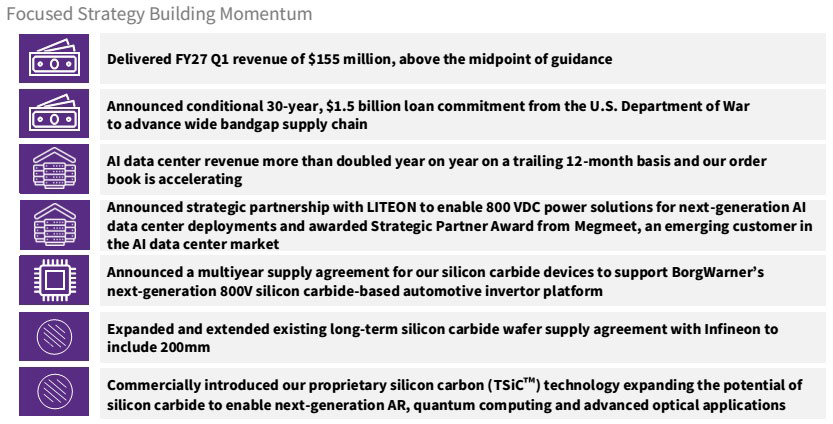
Business highlights during the quarter included:
- announcing a conditional 30-year, $1.5bn loan commitment from US Department of War to advance the domestic supply chain for wide-bandgap semiconductors;
- expanding and extending the existing 150mm long-term silicon carbide wafer supply agreement with Infineon Technologies AG to include 200mm;
- announcing a multi-year supply agreement for silicon carbide devices to support BorgWarner’s next-generation 800V silicon carbide-based inverter platform;
- announcing a strategic partnership with LITEON to enable 800V power solutions for next-generation AI data-center deployments;
- being awarded the Strategic Partner Award in mid-September from Megmeet, an emerging customer in the AI data-center market; and
- commercially introducing proprietary transparent silicon carbide (TSiC) technology expanding the potential of silicon carbide to enable next-generation augmented reality (AR), quantum computing and advanced optical applications.
Net loss cut further
On a non-GAAP basis, gross margin has recovered further, from –26% and –19.9% last quarter to –12.8% despite the only slightly higher revenue base. This is driven by higher utilization (due to a largely completed inventory reduction, plus a more favorable product mix in power devices) and operational improvement initiatives. Under-utilization remains the primary driver, but improving factory utilization is one of the key near-term levers to drive margin expansion.
Operating expenses are down on $66.3m a year ago, but up from $62.3m last quarter to $63.6m, as the firm positions itself for growth.
During the quarter, Wolfspeed completed a previously planned workforce reduction of about 6%, further streamlining operations and aligning costs with current market conditions.
Although it is up on $85.2m ($0.55 per diluted share) a year ago, net loss has been cut further, from $116.9m ($2.26 per diluted share) last quarter to $111.4m ($2.03 per diluted share).
Net cash used in operating activities was $84.2m, although this includes $32m of interest paid during the quarter. Capital expenditure was just $11m (slashed from $103.9m a year ago), focused on maintaining existing manufacturing capabilities. Free cash flow was hence –$96.5m (cut only slightly from –$99.6m a year ago), reflecting ongoing investments in the business and operational requirements.
During the quarter, total cash, cash equivalents and short-term investments hence fell from $1088.6m to $995.1m, although this is still up on $926m a year ago.
Changes in working capital contributed about $60m to cash, mainly from continued inventory reduction. Over the past five quarters, working capital improvements have contributed about $235m. “We have largely completed the working capital optimization initiatives we launched shortly after I joined Wolfspeed,” believes chief financial officer Gregor van Issum.
The conditional 30-year $1.5bn loan commitment from the US Department of War announced in October is “an important milestone that will provide long-term capital to support our strategy while strengthening our capital structure, and one we believe is reflective of the importance of Wolfspeed’s silicon carbide to the US national and economic security,” says van Issum.
“The initial $600m tranche, Tranche A, is expected to refinance the remaining balance of our high-cost first-lien senior secured notes due in 2030. This builds on the reduction we completed in March, which lowered our first-lien debt from $1.1bn to approximately $630m, and would complete our planned refinancing of these notes,” he adds. “The refinancing is expected to deliver more than $50m in annual interest savings and, given the first five years of interest payments will be paid in kind, annual cash interest savings are expected to be approximately $100m.”
“The tranches beyond Tranche A would give us the flexibility to fund a multi-year strategic investment program on a project basis, including scaling our established silicon carbide platform, establishing and expanding domestic GaN [gallium nitride] power device capabilities, advancing GaN-on-SiC RF material technology, and developing domestic radiation-hardening capabilities,” says CEO Robert Feurle. “This is not a program to build additional sites or square footage. It is about capitalizing on our existing capabilities, IP, tooling, and customer relationships we already have, which is fully aligned with the strategic objective we have discussed for several quarters.”
Quarterly revenue break-even point now under $200m
For fiscal second-quarter 2027 (to end-December 2026), Wolfspeed targets revenue of $155–175m, reflecting anticipated growth in core end markets. In particular, the data-center order book is accelerating, reinforcing its position as the firm’s fastest-growing market.
The firm expects sequential gross margin improvement approaching breakeven. Targeted operating expenses are $65–69m, a modest sequential increase driven primarily by the investments to support expected AI data-center growth.
Wolfspeed thinks that, given the improvements it is making and the favorable end-market mix, the break-even quarterly revenue point is a now little under the prior target of $200m. The firm expects to reach this through improved product mix and utilization. Specifically, utilization at the Mohawk Valley Fab needs to be 25–30% to achieve break-even gross margins. “On the equipment utilization, we believe we are well on track to be able to do that,” reckons van Issum. “Fiscal 2027 will be a turning point and the start to more meaningful longer-term growth in both revenue and profitability,” he adds.
“The conditional $1.5bn commitment from the US Department of War, coupled with the multiple long-term supply agreements we announced, support our commitment to returning Wolfspeed to a path of long-term, sustainable growth,” concludes Feurle.
Wolfspeed launches transparent silicon carbide technology for AR and quantum computing
Wolfspeed agrees multi-year deal to supply 1200V silicon carbide devices to BorgWarner
Wolfspeed receives conditional $1.5bn loan commitment from US Department of War
Wolfspeed’s device revenue rebound driven by AI data center business
Wolfspeed and LITEON partner on 800VDC power solutions for hyperscale AI data centers
Wolfspeed cuts quarterly loss after CapEx slashed during restructuring